Financial Planning for Home Improvement Contractors
Financial planning for home improvement contractors builds stability and growth. Call 5106637016 for expert guidance on managing cash flow and reserves.
By Julia Ellis
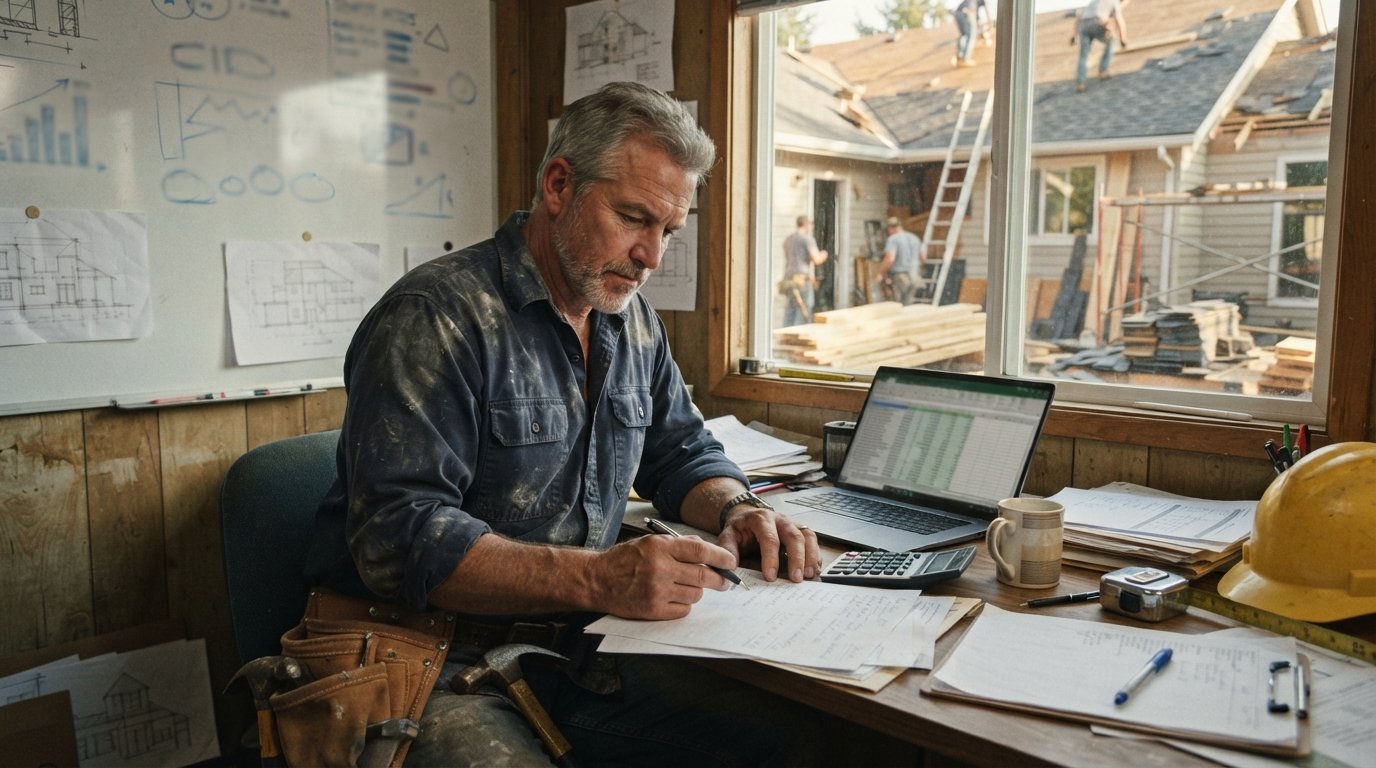
Most home improvement contractors are excellent at building things: framing walls, installing windows, running electrical lines, and managing crews. But ask them about their own finances, and many will admit they are flying blind. The feast-or-famine cycle of construction work makes it tempting to spend heavily during busy months and scramble during slow ones. That approach works until it does not, and when it fails, it fails hard. A single slow quarter can wipe out years of hard work if cash reserves are thin and debt obligations are high.
The contractors who survive and thrive over decades are not necessarily the best craftsmen. They are the ones who treat their business like a financial system, not just a job site. They know their numbers, plan for taxes, build reserves, and invest in growth deliberately. This article walks through the financial planning strategies that separate stable, growing contracting businesses from those that lurch from one paycheck to the next. Whether you run a roofing crew, a bathroom remodeling company, or a full-service renovation firm, these principles apply.
Why Financial Planning Matters More for Contractors Than Most Businesses
Contracting is a capital-intensive, cyclical, and risk-heavy business. You buy materials upfront, pay labor before the customer pays you, and often wait 30 to 60 days for final payment. Meanwhile, you are carrying insurance, vehicle costs, tool replacements, and the constant pressure of finding the next job. Unlike a retail store that collects cash immediately, contractors often finance their clients' projects with their own working capital.
Seasonality adds another layer of complexity. Roofers in northern states may have four productive months and eight months of reduced activity. Bathroom remodelers often see demand spike in spring and fall. HVAC contractors live and die by temperature swings. If your financial plan assumes steady monthly revenue, you will be perpetually surprised and perpetually stressed.
Then there is the tax burden. Contractors are often classified as independent contractors or business owners, which means quarterly estimated taxes, self-employment tax, and the risk of a surprise bill in April if you have not set money aside. Add in the cost of permits, licenses, and insurance, and the margin for error shrinks quickly.
Financial planning for home improvement contractors is not about spreadsheets for the sake of spreadsheets. It is about creating a system that smooths out the bumps, protects you during slow periods, and gives you the confidence to invest in growth when the timing is right.
Build a Cash Reserve That Actually Matches Your Risk
The standard advice for small businesses is to hold three to six months of operating expenses in reserve. For contractors, that is often not enough. Because your revenue is lumpy and your payment cycles are long, you should aim for a reserve that covers your fixed costs during your slowest stretch of the year, plus a buffer for unexpected equipment failures or a project that goes sideways.
Start by calculating your monthly fixed costs: rent or mortgage on your shop or storage, vehicle payments, insurance premiums, loan payments, software subscriptions, and minimum payroll for key staff. Multiply that by the number of months in your slow season, then add 20 to 30 percent. That is your target reserve. If it feels impossibly high, start with one month and build from there. The goal is progress, not perfection.
Where should you keep this reserve? A separate savings account that you do not touch for day-to-day expenses. Do not invest it in stocks or crypto. This money needs to be liquid and stable. If you have a line of credit, treat it as a backup, not as your primary reserve. Lines of credit can be frozen or reduced during economic downturns, exactly when you need them most.
Master Cash Flow Forecasting for Project-Based Work
Cash flow is not the same as profit. You can be profitable on paper and still run out of money if your cash is tied up in unpaid invoices or materials sitting on a job site. Contractors need a rolling cash flow forecast that looks at least 90 days ahead and accounts for the timing of deposits, progress payments, material purchases, and payroll.
Here is a simple framework for building one:
- List every project you have signed or are likely to sign in the next 90 days.
- For each project, map out when you will receive deposits, progress payments, and final payment.
- Map out when you will pay for materials, labor, subcontractors, and permits.
- Compare the two timelines week by week to see where gaps appear.
- Adjust your spending or accelerate collections to close those gaps before they become crises.
This exercise takes an hour or two each month, but it prevents the kind of surprise that forces you to put payroll on a credit card or delay paying a supplier. Many contractors also use this forecast to decide when to take on a new project. If a job will strain cash flow during an already tight month, you can negotiate a larger deposit or schedule the start date later.
If you are looking to expand your pipeline and need a predictable source of new projects, platforms like HomeRemodelingLeads connect contractors with homeowners who are actively seeking renovation services. Having a steady flow of qualified leads makes cash flow forecasting easier because you are not guessing when the next job will appear.
Separate Business and Personal Finances Completely
One of the most common mistakes contractors make is mixing business and personal money. It starts innocently: you use a personal credit card for a business purchase because it is convenient, or you transfer money from the business account to cover a personal expense. Over time, this blurring makes it impossible to know whether your business is actually profitable.
Separate accounts are not just for accounting convenience. They protect you legally, make tax preparation far easier, and give you a clear picture of your business health. Open a dedicated business checking account and a business savings account. Pay yourself a consistent salary or draw, and treat that as a business expense. If you need more money personally, increase your draw deliberately rather than pulling from the business account whenever you need cash.
This discipline also helps when you apply for financing. Lenders want to see clean financials. If your accounts are a jumble of personal and business transactions, you will struggle to qualify for a loan or line of credit when you need one.
Plan for Taxes Quarterly, Not Annually
Taxes are the single biggest financial surprise for many contractors. If you are classified as an independent contractor or you own an S-corp or LLC, you are responsible for quarterly estimated tax payments. Miss those, and you face penalties and interest on top of a large bill in April.
The solution is simple: set aside a percentage of every payment you receive for taxes. A common rule of thumb is 25 to 30 percent, but your actual rate depends on your income, deductions, and entity structure. Work with a CPA who understands construction to determine the right percentage for your situation. Then open a separate tax savings account and transfer that percentage every time you deposit a customer payment.
Do not wait until the end of the quarter to calculate what you owe. If you set aside money with every payment, the quarterly payment becomes a transfer rather than a scramble. This system also protects you from the temptation to spend money that is not really yours.
Invest in Growth Without Overextending
Growth costs money. New equipment, additional crew members, marketing, and lead generation all require upfront investment. The question is not whether to invest, but how much and when. Contractors who grow too fast often collapse under the weight of their own expansion because they take on more work than their cash flow can support.
Before you invest in growth, ask three questions:
- Do I have a reserve that can cover three months of increased fixed costs if revenue does not materialize as quickly as expected?
- Is my current operation profitable enough to fund this investment from cash flow, or will I need financing?
- What is the payback period, and how confident am I in that estimate?
If the answers are not reassuring, consider a smaller step. Instead of hiring three new crew members, hire one. Instead of buying a new truck, lease one. Instead of a massive marketing spend, test a smaller campaign and measure the results. Growth is a series of calculated bets, not a single leap of faith.
For contractors in competitive markets, having a reliable source of high-intent leads can make growth investments less risky. When you know you can fill your pipeline with qualified projects, hiring and equipment purchases become easier to justify.
Leverage Financing Strategically
Debt is not inherently bad. Used wisely, it allows you to take on larger projects, buy equipment that increases efficiency, and smooth out seasonal cash flow. Used poorly, it becomes a trap that consumes your profits and limits your options.
Here are a few guidelines for contractor financing:
- Borrow for assets that generate revenue, not for day-to-day operating expenses. A new work truck or a specialized tool that lets you take on higher-margin jobs is a good investment. Using a credit card to make payroll is a sign of a deeper problem.
- Match the loan term to the life of the asset. Do not finance a 10-year asset with a 2-year loan, and do not finance a 2-year asset with a 10-year loan.
- Keep your debt service below 15 to 20 percent of your monthly revenue. If your loan payments exceed that threshold, you are vulnerable to any downturn.
- Shop around. Banks, credit unions, equipment manufacturers, and online lenders all offer different terms. Do not accept the first offer you receive.
If you are considering a home equity line of credit or a mortgage refinance to fund your business, it is worth understanding how lenders evaluate your personal and business financial profile. Services like MortgageLeads connect mortgage professionals with consumers, which can be a useful resource if you are exploring financing options for a home-based business or investment property.
Track the Right Metrics Every Month
You cannot improve what you do not measure. Most contractors track revenue and maybe gross profit, but that is not enough. To make informed financial decisions, you need a monthly dashboard that includes:
- Revenue by project type and by lead source
- Gross margin per project
- Net profit margin
- Cash on hand and days of operating expenses covered
- Accounts receivable aging (how long customers take to pay)
- Pipeline value (total estimated revenue from signed and pending contracts)
Review these numbers every month, ideally with your accountant or a business advisor. The goal is not to obsess over every fluctuation but to spot trends early. If your gross margin is declining, you can investigate whether material costs are rising or whether you are underpricing jobs. If your accounts receivable aging is getting worse, you can tighten your collection process before it becomes a cash crisis.
Build a Financial Rhythm That Works for You
Financial planning is not a one-time event. It is a rhythm: weekly, monthly, quarterly, and annual habits that keep your business on track. Here is what that rhythm might look like:
- Weekly: Review cash position, send invoices, follow up on overdue payments.
- Monthly: Update cash flow forecast, review financial dashboard, reconcile accounts.
- Quarterly: Make estimated tax payments, review reserve balance, assess progress against annual goals.
- Annually: Review pricing, evaluate insurance coverage, set next year's budget, meet with your CPA for tax planning.
The specifics will vary depending on the size and complexity of your business, but the principle is the same: consistent attention prevents small problems from becoming large ones. Contractors who build this rhythm into their operations sleep better at night and make better decisions during the day.
For contractors in markets like Southern California, where competition is fierce and project values are high, financial discipline is especially important. You can read more about navigating that market in this guide to Home Improvement Los Angeles California, which covers smart upgrades and market-specific considerations.
Financial planning for home improvement contractors is not about becoming an accountant. It is about gaining control over the money that flows through your business so that you can focus on what you do best: building, renovating, and growing a company that lasts. Start with one habit, whether it is building a reserve, forecasting cash flow, or setting aside taxes. Add another next month. Over time, these habits compound into financial stability and the freedom to choose the projects and clients that move your business forward.