Helping Homeowners Finance a Remodeling Project: Contractor Guide
Guide homeowners through financing options to close more remodeling deals. Call 5106637016 for expert assistance.
By Hannah Walsh
Homeowners often stall on remodeling plans not because they lack vision, but because they lack a clear path to pay for the work. Contractors who can guide clients through financing options close more deals, reduce cancellations, and build referral pipelines that last. This guide is written for remodeling professionals who want to become the trusted advisor on project funding, not just the builder. Whether you install kitchens, bathrooms, roofing, or full additions, understanding how homeowners finance a remodeling project gives you a serious competitive edge.
Why Contractors Should Lead the Financing Conversation
Most homeowners start a remodel with excitement, then hit a wall when they see the estimate. If your only answer is a payment schedule, the project may die in the proposal stage. Contractors who proactively discuss financing keep the momentum alive. You are not a lender, and you should never present yourself as one, but you can educate, connect, and guide.
The contractors who win more bids are the ones who remove friction. When a homeowner knows there are multiple ways to fund a kitchen remodel, a roof replacement, or a bathroom update, they stop seeing the price as a dead end. They start seeing it as a manageable plan. That shift in mindset is often the difference between a signed contract and a lost opportunity.
Financing also protects your business. Projects funded through structured loans or credit lines tend to have fewer mid-project payment disputes. Homeowners who have secured funds upfront are less likely to pause work or request scope changes they cannot afford. By guiding clients early, you reduce the risk of stalled jobs and unpaid invoices.
Common Financing Options Homeowners Can Use
There is no single best way to pay for a remodel. The right choice depends on the homeowner's equity, credit profile, savings, and comfort with debt. Your role is to present the landscape clearly so they can make an informed decision. Here are the most common paths homeowners explore.
- Cash savings: The simplest option. No interest, no applications, no debt. However, many homeowners do not have enough liquid cash for a full remodel and may need to combine savings with other funding.
- Home equity loans and HELOCs: These use the home's equity as collateral. They often have lower interest rates than personal loans. A home equity loan gives a lump sum, while a HELOC works like a credit line the homeowner can draw from as needed.
- Cash-out refinancing: The homeowner replaces their existing mortgage with a larger one and takes the difference in cash. This can work well when rates are favorable and the homeowner plans to stay long term.
- Personal loans: Unsecured loans that do not require home equity. They are faster to obtain but usually carry higher interest rates. Best for smaller projects or homeowners with limited equity.
- Credit cards: Convenient but expensive if balances are carried. Suitable only for small updates or short-term bridging.
- Government-backed programs: Some FHA, VA, and USDA programs allow renovation costs to be rolled into a purchase or refinance. These are niche but valuable for specific buyers.
Each option has trade-offs. A homeowner with strong equity may prefer a HELOC for flexibility. A younger buyer with limited equity might choose a personal loan to avoid touching their mortgage. Your job is not to push one product but to help them see which fits their financial situation. When you can speak intelligently about these choices, you become a resource, not just a vendor.
For contractors who want to connect homeowners with lending professionals, building relationships with mortgage brokers and loan officers is smart. Platforms like MortgageLeads help lenders connect with high-intent borrowers, and those same networks can be a referral source for your remodeling business. When a homeowner is already exploring a cash-out refinance or home equity line, they are prime candidates for a remodel conversation.
How to Introduce Financing Without Sounding Pushy
The financing conversation should feel like a service, not a sales tactic. Timing matters. Bring it up after you have presented the scope and the homeowner has expressed genuine interest. If you lead with financing before they understand the value, it can feel transactional. If you wait until they see the price and freeze, it can feel like a rescue attempt.
A simple approach is to include a financing section in your proposal. Add a line that says, "Many homeowners choose to fund their remodel through home equity or personal loans. I can connect you with a trusted lender if you would like to explore options." This normalizes the idea without pressure. It also signals that you understand real-world budgets.
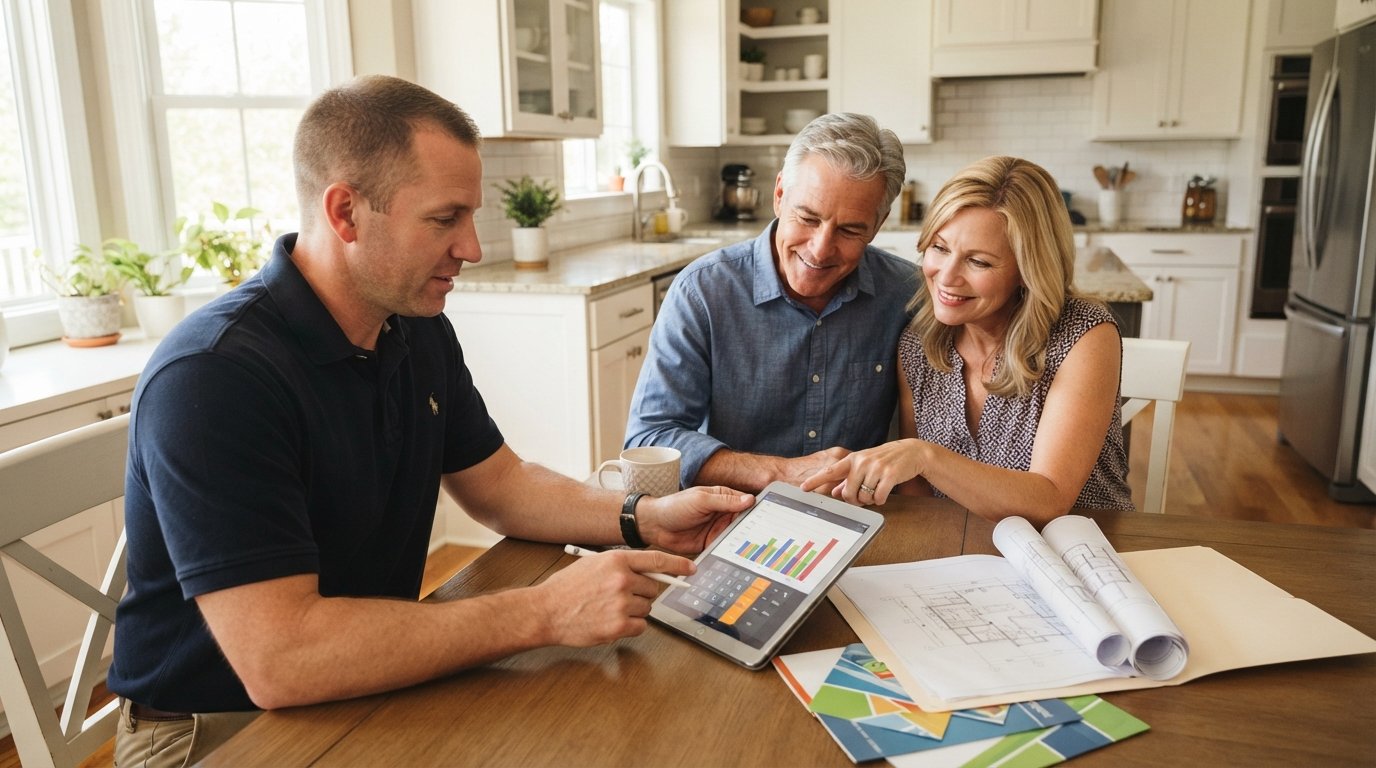
During the consultation, ask open-ended questions. "Have you thought about how you would like to fund the project?" or "Would it help if I shared a few financing paths that other clients have used?" These questions invite dialogue. They also give you information about the homeowner's financial comfort zone, which helps you tailor your recommendations.
Never quote specific interest rates or terms unless you are licensed to do so. Instead, speak in general terms: "Home equity lines often have lower rates than personal loans, but they require equity and a credit check." Keep the focus on education and connection, not advice.
Qualifying Homeowners for Financing Readiness
Not every homeowner is ready to finance a remodel. Some need to improve their credit, pay down debt, or build more equity. As a contractor, you can help them see the path forward without overstepping. A simple qualification conversation can save everyone time.
Ask about their timeline, their comfort with monthly payments, and whether they have explored lending options. If they have not, offer to connect them with a lender who can pre-qualify them. Pre-qualification is not a full approval, but it gives the homeowner a realistic budget range. That range helps you design a project that fits, rather than proposing a dream remodel that cannot be funded.
For homeowners who are not ready, a referral to a credit counselor or financial advisor can be a goodwill gesture. They may come back in six months or a year, and they will remember that you helped them without pressure. That is how you build long-term referral relationships.
If you work in niche categories like bathroom remodeling or kitchen remodeling, financing readiness is especially important. These projects often have emotional urgency, and homeowners may be tempted to overextend. Guiding them toward sustainable funding protects both of you.
Partnering With Lenders and Lead Platforms
Your financing strategy does not have to be solo. Partnering with lenders, mortgage brokers, and lead generation platforms can expand your reach and improve conversion. When you have a trusted lender to refer, you can move faster and reduce the back-and-forth that kills deals.
Lead platforms like HomeRemodelingLeads connect contractors with homeowners who are actively seeking renovation services. These leads are often pre-qualified and segmented by project type, which means you are talking to people who have already raised their hand. When you combine that with a financing conversation, you increase the odds of closing.
Consider building a small network of financial professionals you can call on. A mortgage broker who specializes in renovation loans, a credit union that offers competitive HELOCs, and a personal loan officer who can work with lower-credit homeowners. When you have these relationships, you can offer options without becoming a lender yourself.
If you are looking to grow your remodeling business, investing in high-intent leads is one of the most direct paths. You can explore categories like roofing, windows, bathroom remodeling, solar, flooring, and HVAC. Each category has its own financing nuances, and understanding them makes you a more valuable partner to homeowners.
Building a Financing-Friendly Contractor Brand
Homeowners talk. When you are known as the contractor who helps with financing, referrals grow. You become the person someone calls when their cousin needs a new roof but is not sure how to pay for it. That reputation is built on small actions: mentioning financing in your proposal, following up with lender connections, and celebrating when a homeowner finds a path that works.
Your website and marketing should reflect this. Add a page or section that explains financing options in plain language. Include a call to action that invites homeowners to ask about funding. Train your sales team to bring up financing naturally. These steps signal that you are a full-service partner, not just a builder.
It also helps to track which financing paths lead to closed deals. If most of your clients use HELOCs, lean into that. If personal loans are common, build relationships with lenders who specialize in them. Data-driven decisions make your financing guidance more effective over time.
For remodelers who want to scale, combining financing guidance with a steady flow of qualified leads is the winning formula. You can focus on what you do best, building, while your lender partners handle the funding details. The homeowner gets a seamless experience, and you get a signed contract with fewer surprises.
Common Mistakes to Avoid
Even well-intentioned contractors can stumble when discussing money. Avoid these common pitfalls to keep the conversation productive.
- Promising specific rates or terms: Unless you are a licensed lender, do not quote numbers. Speak in ranges and generalities.
- Pushing one option too hard: Every homeowner is different. Present multiple paths and let them choose.
- Ignoring credit realities: If a homeowner has challenged credit, do not dismiss them. Connect them with a lender who works with a range of profiles.
- Waiting until the last minute: Bring up financing early, ideally during the design or proposal phase.
- Forgetting to follow up: If you refer a homeowner to a lender, check in. A quick follow-up can keep the process moving.
These mistakes are easy to fix with a little preparation. Create a simple financing script, build a lender referral list, and train your team. The payoff is worth it.
Final Thoughts on Financing and Remodeling Success
Helping homeowners finance a remodeling project is not about becoming a financial expert. It is about being a trusted guide who removes obstacles. When you can speak confidently about home equity, personal loans, and refinancing, you become more than a contractor. You become a partner in the homeowner's vision.
Start small. Add a financing line to your proposal. Ask one lender to coffee. Mention options during your next consultation. Over time, these habits compound into a reputation that attracts better clients and bigger projects. And when you combine that with high-quality leads from a platform like HomeRemodelingLeads, you have a system that supports steady growth.
If you are ready to take the next step, explore how our lead categories can connect you with homeowners who are already planning their remodel. From roofing to bathroom remodeling, the right leads plus the right financing conversation can transform your business.