Job Costing and Cash Flow for Remodeling Contractors
Job costing and cash flow for remodeling contractors decide whether busy jobs become real profit. Call 5106637016 for expert guidance.
By Hannah Walsh
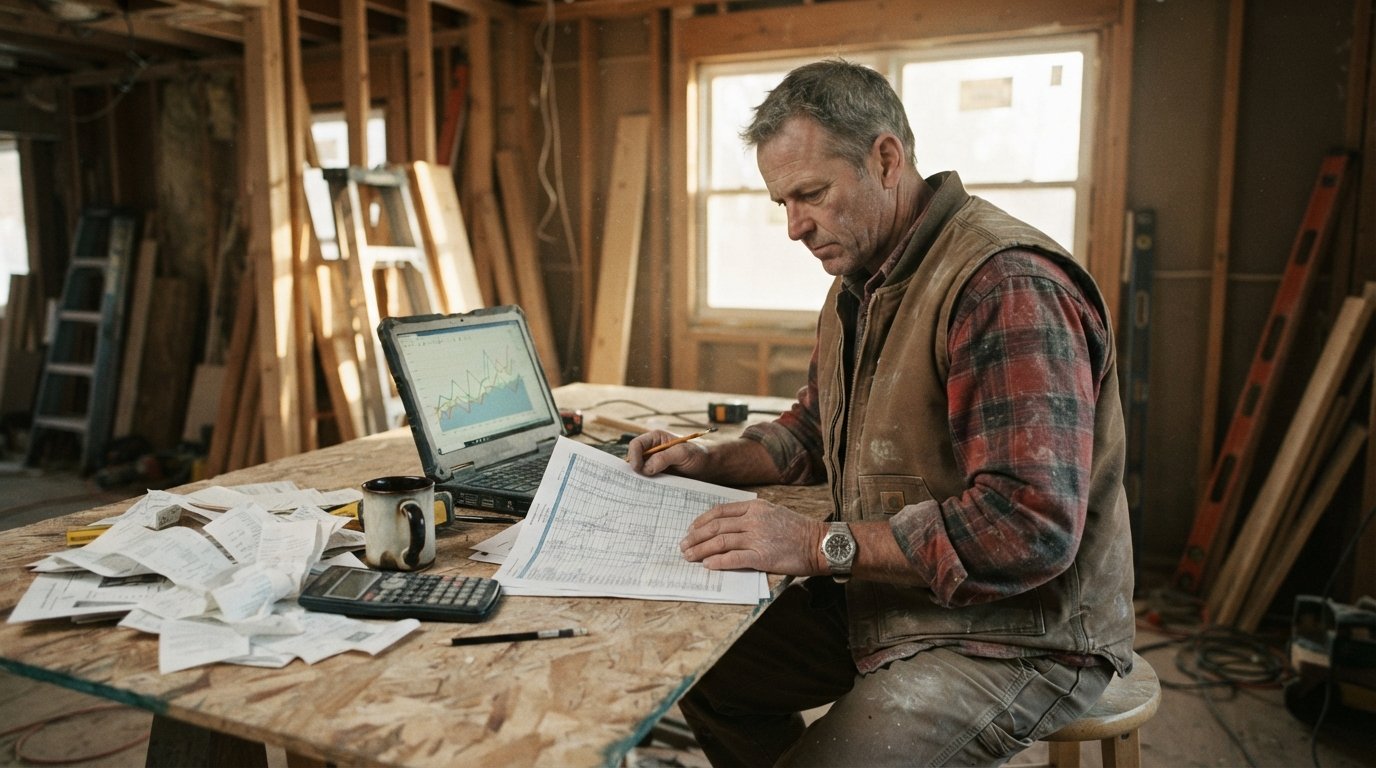
Most remodeling contractors are excellent at building things. Fewer are excellent at tracking what those things actually cost until the job is finished, and by then the profit is already gone. Job costing and cash flow for remodeling contractors are the two financial systems that separate companies that grow from companies that stay busy and broke. One tells you whether a specific project made money. The other tells you whether you can pay your crews, your suppliers, and yourself on time while that project is still running.
This guide breaks down how to build both systems without hiring a full-time accountant. You will learn how to structure a job cost report, how to forecast cash flow around progress payments and material draws, and how to plug the leaks that quietly drain margin on kitchen, bathroom, roofing, and addition projects.
Why Job Costing and Cash Flow Are Two Different Problems
Job costing answers a single question: did this project make money? Cash flow answers a different question: do I have money in the bank right now? A contractor can be profitable on paper and still unable to make payroll because the profit is tied up in a job that is 80 percent complete but only 50 percent billed. That gap is where most remodeling businesses get into trouble.
Job costing is a backward-looking and forward-looking discipline. It compares estimated costs to actual costs by category: labor, materials, subcontractors, permits, equipment, and overhead allocation. Cash flow is a timing discipline. It maps when money leaves your account against when money arrives from clients, lenders, or insurance.
You need both because they solve different failure modes. Weak job costing produces jobs that look fine until you add up the receipts. Weak cash flow management produces jobs that are profitable but unfundable, which is just as fatal. The contractors who survive downturns and scale during booms run both systems on every project, not just the big ones.
Building a Job Costing System That Actually Gets Used
A job costing system only works if the data is captured in real time. If your foreman is handing you a stack of receipts two weeks after a job closes, you are doing archaeology, not accounting. The goal is a simple structure that crews and office staff can feed daily without friction.
Start by breaking every project into cost codes. These are the buckets you will compare against your estimate. For a typical bathroom remodel, your cost codes might include demolition, rough plumbing, rough electrical, drywall, tile labor, tile material, fixtures, vanity and countertop, paint, and cleanup. For a roofing job, they might be tear-off, disposal, decking, underlayment, shingles, flashing, ventilation, and labor.
Once cost codes exist, you need a way to capture three things on every transaction: the job, the cost code, and whether it was committed or actual. Committed costs are purchase orders and subcontractor agreements you have signed but not yet paid. Actual costs are invoices you have received. Tracking both prevents the classic surprise where a job looks profitable until the final supplier bill arrives.
- Assign every employee and subcontractor a job number and cost code before they start work.
- Require receipts and packing slips to be photographed and uploaded the same day.
- Reconcile committed costs weekly so you see the true remaining budget, not just cash spent.
- Review a job cost report at 25 percent, 50 percent, and 75 percent completion, not only at the end.
That review cadence is what turns job costing from a post-mortem into a management tool. If you are 50 percent through a kitchen remodel and labor is already at 70 percent of budget, you can change how the remaining work is staffed, subbed out, or sequenced. Waiting until the final invoice means the only decision left is whether to absorb the loss or argue with the client.
Choosing the Right Job Costing Method for Remodeling Work
Remodeling is not new construction. You rarely have a clean set of drawings and a fixed scope from day one. Change orders, hidden conditions, and client selections move the target constantly. That means your costing method has to be flexible enough to absorb change without losing the thread of profitability.
Most remodeling contractors do best with a hybrid of estimated cost at completion and percentage-of-completion accounting. At the start of the job, you lock in an estimated total cost. As the job progresses, you compare actual costs plus committed costs plus estimated cost to complete against that original estimate. The difference is your projected gross profit, and you can see it moving in real time.
For smaller jobs under a few weeks, a simple job ledger with cost codes is enough. For larger additions or whole-house renovations, you want a system that separates hard costs (labor, materials, subs) from soft costs (permits, design, temporary utilities) and allocates overhead consistently. Pick a method and apply it to every job so your historical data is comparable. Comparability is what lets you bid the next job with confidence instead of guessing.
Cash Flow Forecasting for Remodeling Projects
Cash flow in remodeling is lumpy by nature. You front-load materials, labor, and permits, then collect in draws tied to milestones. If your draw schedule does not match your spend curve, you are financing your clients' projects out of your own pocket, often at credit card interest rates.
The fix is a rolling 13-week cash flow forecast. Every week, you project cash in from signed contracts, approved change orders, and pending draws, and cash out for payroll, supplier terms, subcontractor payments, equipment, insurance, and overhead. The forecast does not need to be perfect. It needs to be updated weekly so you see a shortfall coming while you still have options.
Build your forecast around your actual payment terms. If your supplier gives you net 30 and your client pays draws in 10 days after inspection, you have a timing gap to plan for. If you are working on insurance restoration, the gap can be even longer because the scope has to be approved, adjusted, and funded before your final check arrives.
- List every active job and its remaining billing milestones.
- Estimate the date each milestone will be invoiced and the date payment is realistically expected.
- List every recurring and job-specific cash outflow by week.
- Subtract outflows from inflows to find your net weekly position.
- Identify the lowest point in the 13-week window and arrange a line of credit or deposit structure to cover it.
That lowest point is the number that matters. If your forecast shows a $40,000 dip in week six, you can either negotiate a mobilization deposit, schedule a smaller job to close in that window, or draw on a line of credit before you need it. Contractors who skip this step often discover the dip when a payroll check bounces.
Deposits, Draw Schedules, and Progress Billing
Your contract payment structure is the single biggest lever on remodeling cash flow. A 10 percent deposit on a $60,000 kitchen remodel does not cover the first week of demolition, dumpster rental, and material orders. A deposit that covers mobilization and initial material purchases keeps you from financing the job yourself.
Draw schedules should be tied to completed milestones, not calendar dates. "Framing complete," "rough-ins passed inspection," and "cabinets set" are billable events. "Three weeks in" is not. Milestone billing gives you a defensible reason to invoice and gives the client a clear picture of what they are paying for.
Progress billing also protects you on long jobs. If a project runs eight weeks, you should be billing at least every two weeks. Monthly billing on a fast-moving job means you are always behind on cash. Weekly billing on smaller jobs, or biweekly on larger ones, keeps the cash engine running. Pair this with clear change order procedures so additional work is priced, approved, and billed before it is performed, not after.
Controlling the Three Biggest Cash Flow Killers
Three problems account for most remodeling cash flow crises: change orders performed before they are approved, material over-ordering without a purchase order system, and slow collection on retainage or final payments. Each one is fixable with process, not more revenue.
Change orders should be written, priced, signed, and deposited before work begins. If a client asks for a mid-job upgrade, the answer is not no, it is "yes, here is the change order and the revised deposit." Contractors who do this protect their margin and their cash. Contractors who do not end up arguing about money at the end of the job, which is the worst possible time to have that conversation.
Material controls matter because materials are often the largest line item on a remodel. A purchase order system with committed cost tracking prevents the classic scenario where three crew members each order the same trim package and you end up with $4,000 of extra material sitting in the shop. It also gives you leverage with suppliers when you can show them accurate volume forecasts.
Final payment collection is the last leak. Build your contract so that final payment is due on substantial completion, with a clearly defined punch list window. Do not let retainage sit for 60 days while you chase small fixes. Schedule the punch list walk immediately, complete it within a week, and invoice the same day. If you need capital to bridge a gap while a large job is finishing, options like mortgage lead networks are not relevant to your business, but a contractor-specific line of credit or equipment financing is worth exploring with your banker.
Software and Tools That Make Both Systems Work
You do not need enterprise software to run job costing and cash flow, but you do need something better than a spreadsheet that only you understand. The right tool depends on your volume and how many people touch the numbers.
At minimum, you want accounting software that supports job costing (QuickBooks Online with Projects, for example), a field app for time and receipt capture, and a simple cash flow template that you update weekly. As you grow past a few crews, look at construction-specific platforms that tie estimates, purchase orders, change orders, and job cost reports together. The goal is one source of truth, not five systems that do not talk to each other.
When you are evaluating tools, ask three questions: Can my foreman enter time and receipts from a phone in under two minutes? Can I see committed costs versus actual costs by job code? Can I export a cash flow forecast without rebuilding it by hand every week? If the answer to any of those is no, keep looking.
Using Job Costing Data to Win Better Jobs
Once you have a year of clean job cost data, your estimating gets sharper. You stop bidding from memory and start bidding from history. You know that your average bathroom remodel takes 18 labor days, not 14. You know that tile subcontractors in your area run 12 percent over estimate on complex patterns. You know which job types produce your best gross margin and which ones you should stop chasing.
That data also helps you evaluate lead sources. If you are buying remodeling leads, you can compare cost per lead against cost per closed job and actual gross profit per job type. A lead that costs $45 but closes into a $30,000 roofing job at 35 percent margin is a better investment than a $15 lead that closes into a $4,000 job at 15 percent margin. Job costing is what lets you make that comparison with numbers instead of gut feel.
If you are new to buying leads or want to sharpen how you evaluate contractors and lead quality, our guide on how to compare remodeling contractors without regret walks through the questions and red flags that matter, and the same framework applies to evaluating lead providers.
Track three metrics per lead source: cost per lead, close rate, and average gross profit per closed job. Review them quarterly. Cut sources that do not produce profitable jobs, even if the leads are cheap. Double down on sources that produce fewer but better jobs.
Putting It Together: A Weekly Financial Rhythm
The contractors who master job costing and cash flow do not do anything exotic. They just do simple things consistently. A weekly rhythm keeps both systems alive and prevents small problems from becoming existential ones.
Monday: review the 13-week cash flow forecast and update it with any new contracts, draws, or large expenses. Tuesday: reconcile job cost reports for active jobs and flag any cost code running over budget. Wednesday: follow up on outstanding invoices and pending draws. Thursday: review change orders and purchase orders for accuracy and approval. Friday: enter the week's receipts, timesheets, and supplier invoices so the data is clean going into the weekend.
That rhythm takes a few hours a week once it is set up. It replaces the end-of-quarter panic, the surprise tax bill, and the awkward conversation with a subcontractor who has not been paid. More importantly, it gives you the confidence to take on bigger jobs, hire more crews, and grow without wondering whether the money will be there when you need it.
Job costing and cash flow for remodeling contractors are not accounting chores. They are the operating system of a healthy remodeling business. Build them, run them weekly, and let the numbers tell you where to grow next.