Roof Replacement Financing Options for Homeowners
Compare roof replacement financing options for homeowners, from loans to HELOCs. Call (510)-663-7016 for expert guidance.
By Adam Miller
Staring at a quote for a new roof can feel like a punch to the gut. The numbers are big, the timeline is tight, and the last thing you want is to drain your savings or put the project on a high-interest credit card. The good news is that roof replacement financing options for homeowners have never been more varied, and choosing the right one can turn a stressful expense into a manageable monthly payment. Whether you are a homeowner weighing a loan against a HELOC, or a contractor trying to guide clients toward a decision, understanding the landscape is the first step toward a successful project.
The stakes are high. A roof protects everything underneath it, and delaying replacement can lead to leaks, mold, and structural damage that cost far more than the roof itself. Yet rushing into the wrong financing deal can saddle you with unnecessary fees or a rate that balloons over time. This guide breaks down the most common paths, explains how each one affects your conversation with a roofer, and flags the red flags to watch for before you sign anything.
The Main Financing Paths, Compared
When homeowners start shopping for roof replacement financing options, they typically encounter three broad categories: personal loans, home equity lines of credit (HELOCs), and contractor-arranged financing. Each has a different structure, approval process, and impact on your wallet. Understanding these differences before you request quotes will help you ask better questions and avoid surprises at the closing table.
Personal loans are unsecured, meaning you do not pledge your house as collateral. That makes them faster to obtain and less risky in terms of losing your home, but interest rates tend to be higher than secured options. HELOCs, by contrast, use your home equity as collateral and often come with lower rates and flexible draw periods. Contractor financing is a third route, where the roofing company partners with a lender to offer promotional terms, sometimes with zero percent interest for a limited time. Each option suits a different financial profile, and the right choice depends on your credit, your equity, and how quickly you need the funds.
- Personal loans: Unsecured, fixed rates, fast approval, higher APR.
- HELOCs: Secured by home equity, variable or fixed rates, lower APR, longer approval timeline.
- Contractor financing: Arranged through the roofer, promotional rates, convenience but potential deferred interest.
Beyond these three, some homeowners tap into credit cards with zero percent introductory offers or borrow from retirement accounts. These are rarely ideal for a roof replacement because the risks (high post-promotion rates or early withdrawal penalties) often outweigh the short-term savings. The key is to match the financing term to the life of the roof: a 20-year loan for a roof that lasts 25 years can make sense, but stretching payments over 30 years may cost more in interest than the roof is worth.
How Financing Shapes the Contractor Conversation
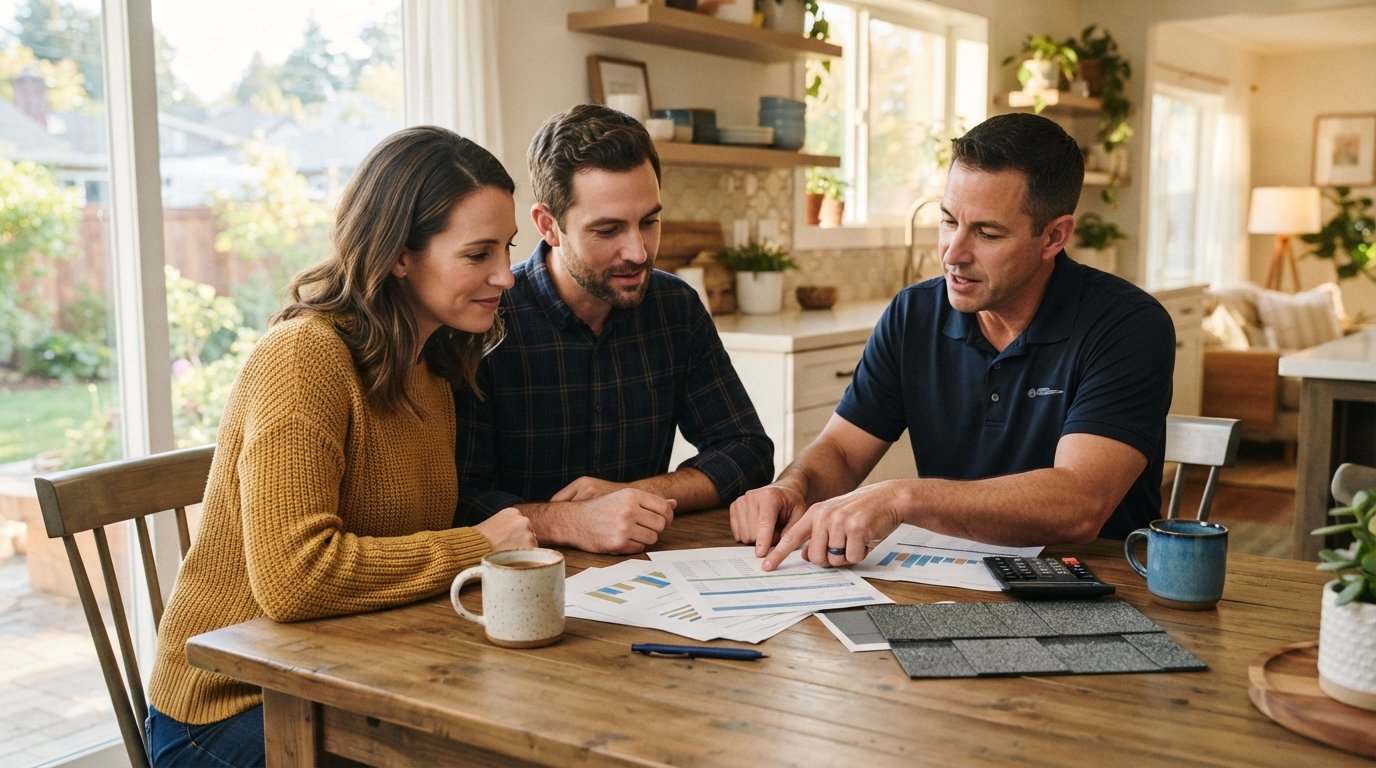
Financing is not just a homeowner issue; it directly affects how roofing contractors scope and sell their projects. When a homeowner has pre-approved financing, the conversation shifts from "Can I afford this?" to "Which materials and timeline work best?" That shift can shorten the sales cycle and reduce the chance of a project stalling after the estimate. Roofers who understand this dynamic are better positioned to guide clients toward solutions that fit their budget without compromising on quality.
For contractors, being fluent in roof replacement financing options for homeowners is a competitive advantage. It allows you to offer payment plans that keep the project moving, and it signals that you understand the customer's full situation, not just the shingle count. Many roofers partner with third-party lenders to provide on-the-spot financing applications, which can be a powerful closing tool. However, it is important to be transparent about terms and never pressure a homeowner into a financing product they do not understand.
Homeowners, in turn, should bring their financing questions to the contractor conversation early. Ask whether the roofer offers in-house financing, which lenders they work with, and whether there are any fees for using a particular payment method. A reputable contractor will welcome these questions and provide clear answers. If you are still in the process of finding a reliable roofer, resources like a homeowner's guide to lead generation can help you vet contractors before you get to the financing stage.
What Roofers Should Know About Homeowner Financing Readiness
From a contractor's perspective, not all homeowners arrive at the estimate with the same level of financial preparation. Some have already researched loans and have a pre-approval letter in hand; others are just beginning to wonder how they will pay for the project. Recognizing these differences can help roofers tailor their approach and avoid wasted time on projects that may not close.
Financing readiness often correlates with the homeowner's credit profile, equity position, and urgency. A homeowner with a leaking roof and good credit may be motivated to move quickly on a personal loan, while someone planning a replacement for next spring might prefer a HELOC that they can draw on later. Roofers who ask a few simple questions about timeline and budget can gauge which financing path is most likely to work and adjust their follow-up accordingly.
It is also worth noting that financing readiness affects lead quality. Contractors who purchase roofing leads from platforms like HomeRemodelingLeads often find that homeowners who have already explored financing options are more serious and more likely to convert. That is why some roofers prioritize leads where the homeowner has indicated a budget or a willingness to finance. Understanding this connection can help contractors refine their lead-buying strategy and focus on prospects who are ready to move.
Red Flags in Roof Replacement Financing Offers
Not every financing offer is created equal, and some come with terms that can hurt homeowners in the long run. The most common trap is deferred interest: a promotional offer that advertises zero percent for 12 or 18 months but retroactively charges interest from the original purchase date if the balance is not paid in full by the deadline. Homeowners who miss the payoff date by even a day can end up owing more than they borrowed.
Another red flag is excessive fees. Some lenders charge origination fees, application fees, or prepayment penalties that are not always disclosed upfront. A reputable lender will provide a clear breakdown of all costs before you sign. Similarly, be wary of contractors who push a specific lender without explaining why or who refuse to provide written terms. High-pressure tactics, such as claiming the offer expires today, are a sign to walk away and do more research.
Homeowners should also watch for liens. When you finance a roof through a contractor, the lender may place a lien on your home until the loan is repaid. While this is standard for some secured loans, it is important to understand the implications if you plan to sell or refinance. Always read the fine print and ask questions about anything that seems unclear. And remember: if a deal sounds too good to be true, it probably is.
For contractors, steering clients toward reputable financing partners is part of protecting your own reputation. Recommending a lender with predatory terms can damage trust and lead to negative reviews. Instead, build relationships with lenders who offer transparent, fair products, and be prepared to explain the basics to homeowners who are new to the process. If you are looking for resources to share with clients, consider pointing them to educational materials that explain insurance lead generation and other financial topics, though the focus here should remain on roofing-specific financing.
Matching the Financing to the Project and the Homeowner
The best financing option is the one that fits both the project timeline and the homeowner's overall financial picture. A roof replacement is a significant investment, often ranging from $5,000 to $15,000 or more depending on the size and materials. Stretching that cost over 10 or 15 years can make the monthly payment manageable, but it also means paying interest for a decade. Homeowners should weigh the monthly payment against the total cost of borrowing and consider whether paying off the loan early is an option.
For older homeowners or those on fixed incomes, a HELOC may offer the lowest monthly payment, but it also puts the home at risk if payments are missed. Personal loans provide predictability with fixed rates and terms, which can be easier to budget for. Contractor financing can be convenient, but it is important to read the terms carefully and compare them to what you could get on your own. In some cases, a combination of approaches (for example, a small personal loan plus savings) can be the most cost-effective route.
Finally, homeowners should not overlook the importance of getting multiple quotes, both for the roof itself and for financing. Just as you would compare roofing estimates, compare loan offers from at least two or three lenders. This simple step can save hundreds or thousands of dollars over the life of the loan. And if you are working with a contractor who offers financing, ask for the lender's terms in writing so you can compare them side by side with other options.
Roof replacement financing options for homeowners are diverse, and the right choice depends on your credit, equity, timeline, and comfort with risk. By understanding the pros and cons of each path and watching for red flags, you can secure the funds you need without compromising your financial future. Contractors who educate themselves on these options can better serve their clients and close more projects. Whether you are a homeowner planning a replacement or a roofer looking to improve your sales process, the key is to approach financing with the same care you would apply to the roof itself: thoroughly, transparently, and with a focus on long-term value.