Solar Energy Leads Credit Rating And Electricity Bill Data Explained
Solar energy leads credit rating and electricity bill data explained: size systems and pick financing before the survey. Call (510)-663-7016 for expert help.
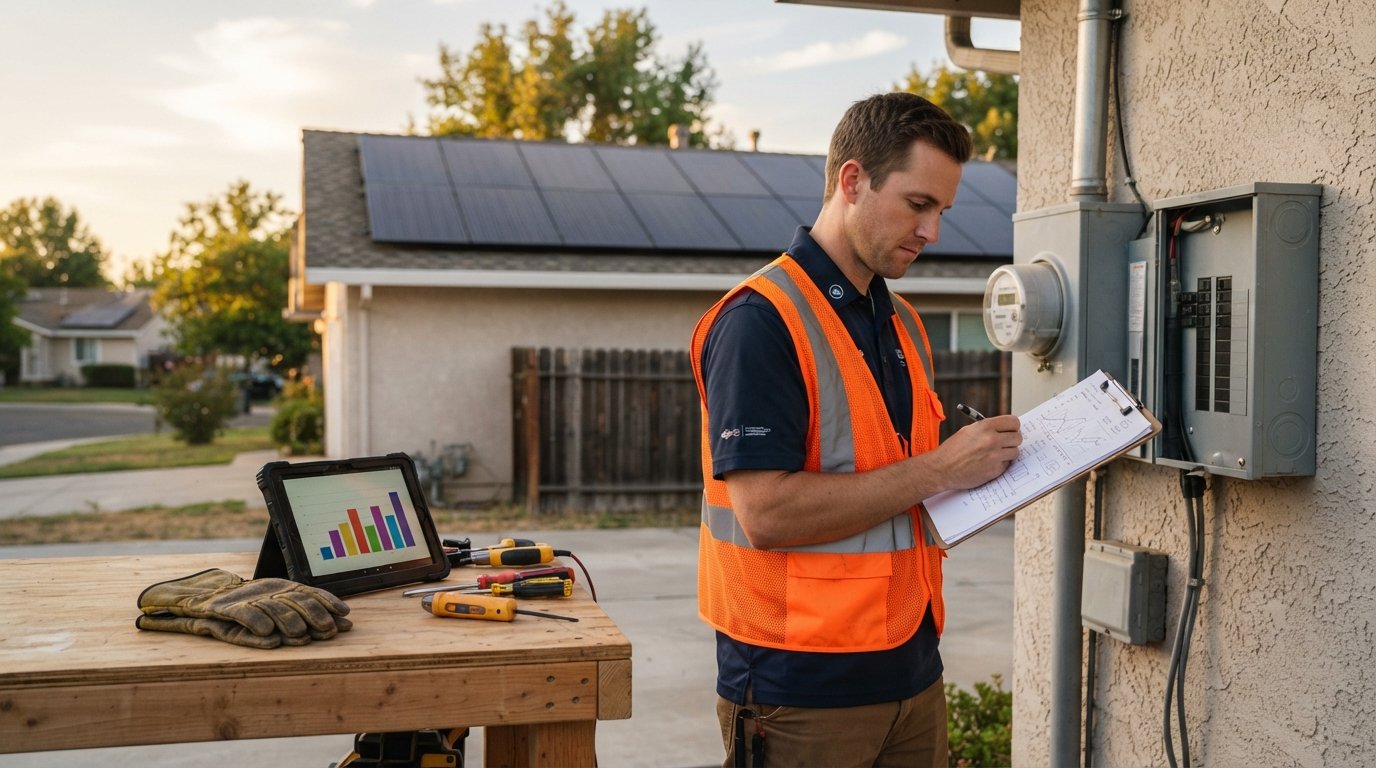
Solar installers know the frustration of driving to a site survey only to discover the homeowner has a $60 monthly electric bill or a credit score that rules out financing. Every wasted trip costs fuel, time, and a slot that could have gone to a qualified buyer. The data attached to a solar lead, specifically the electricity bill range and credit rating tier, exists to prevent that waste. Understanding what these fields mean and how to act on them separates contractors who close at 25 percent from those who close at 8 percent.
This guide breaks down the two most misunderstood data points in residential solar lead generation. You will learn how to read utility bill ranges to size a system before you knock on a door, how credit tiers shape your financing conversation, and when a lead deserves an early disqualification rather than a follow-up call. The goal is not to become a credit analyst or a utility auditor. The goal is to spend your sales hours with homeowners who can actually buy.
Why Electricity Bill And Credit Signals Matter Before A Site Survey
A solar site survey is an expensive step in the sales process. You or a technician travel to the property, inspect the roof, measure shade, check the electrical panel, and spend 45 to 90 minutes gathering information. If the homeowner's electric bill is $70 per month and their roof needs replacement, the survey confirms what the lead data already told you: this is a low-value or no-value project. The bill range and credit tier are pre-survey filters that protect your calendar.
Electricity consumption is the single strongest predictor of system size and project revenue. A homeowner paying $300 per month needs a system roughly four times larger than a homeowner paying $75 per month. Larger systems mean larger contracts, higher margins, and better commission economics for your sales team. Credit rating, meanwhile, predicts whether the homeowner can access financing products, which is how the vast majority of residential solar installations get paid for. A homeowner with a 580 credit score and a $250 electric bill is a different sales conversation than one with a 760 score and the same bill.
When these two data points arrive with the lead, you can rank your pipeline before making a single call. High bill plus high credit equals priority outreach. Low bill plus low credit equals disqualify or nurture. Everything in between gets a phone call with the right expectations. Solar installers who buy leads through a platform like solar installation leads should treat these fields as the first stage of qualification, not an afterthought.
Reading Utility Bill Ranges To Size A System
Solar lead providers typically report electricity bills in ranges rather than exact dollar amounts. A common structure looks like $0 to $100, $101 to $200, $201 to $300, and $300 plus. These ranges are not arbitrary. They map to system sizes, roof space requirements, and financing amounts, and they let you estimate project scope before the site survey.
Here is a practical framework for translating a bill range into an expected system size, using a national average residential rate of roughly 16 to 17 cents per kilowatt hour. Actual rates vary significantly by state, so adjust these figures for your service area.
- $0 to $100 per month: Roughly 500 to 600 kWh monthly consumption, translating to a 4 to 5 kW system. Small project, often marginal economics, sometimes better suited to a partial offset or a battery-only conversation.
- $101 to $200 per month: Roughly 600 to 1,200 kWh, translating to a 5 to 8 kW system. This is the core residential solar sweet spot in many markets.
- $201 to $300 per month: Roughly 1,200 to 1,800 kWh, translating to an 8 to 12 kW system. Strong project value, often with pool pumps, electric heat, or EV charging in the load profile.
- $300 plus per month: Above 1,800 kWh, translating to 12 kW and up. These are premium projects that justify priority scheduling and senior sales reps.
These estimates assume average sun exposure and typical roof orientation. A high-bill lead in a shaded or north-facing property may still require a smaller usable system, and a low-bill lead in an exceptionally sunny market may offset a larger share of usage than the raw number suggests. Use the bill range to set expectations, then let the site survey confirm the design.
Bill range data also reveals consumption patterns that affect the sales pitch. A homeowner with a $280 bill in a mild climate likely has electric resistance heat, a pool, or an EV. Those loads create a natural conversation about battery storage and time-of-use rate optimization, which raises average contract value. A homeowner with a $90 bill may be a retiree on a fixed income looking for bill stability rather than maximum offset. The same data point supports two entirely different presentations.
Using Credit Tier To Decide Financing Conversations
Credit rating data on a solar lead usually arrives as a tier or range rather than a raw score. Common reporting formats include bands like below 600, 600 to 649, 650 to 699, 700 to 749, and 750 plus. Some providers report only a tier label such as prime, near-prime, or subprime. Whatever the format, the purpose is the same: tell you which financing products the homeowner can realistically access before you invest hours in a proposal.
Financing availability drives the entire residential solar sales model. Most homeowners do not write a check for a $25,000 system. They use secured loans, unsecured loans, leases, power purchase agreements, or home equity products, and each of those products has a credit floor. When you know the tier in advance, you can steer the conversation toward the product that will actually get approved instead of presenting a loan the homeowner will be denied for three days later.
- Tier 750 plus: Lead with unsecured and secured loan products at competitive rates. This homeowner has options and will likely compare offers, so speed and rate transparency matter.
- Tier 700 to 749: Loan products remain viable with slightly higher rates. Prepare a secondary option such as a lease or PPA in case the loan approval comes back with conditions.
- Tier 650 to 699: Unsecured loans become difficult. Focus on secured loans, leases, and PPAs, and set expectations about rate ranges early in the conversation.
- Tier 600 to 649: Lease and PPA products are the primary path. Some lenders offer secured options with larger down payments. Screen for co-signers or co-borrowers during the first call.
- Below 600: Cash purchases, co-signer arrangements, or disqualification. Present the cash option once, and do not build a proposal around financing that will not materialize.
Credit tier also affects how you frame savings. A homeowner in the 750 plus band can often achieve a loan payment below their current electric bill from day one, which is a powerful and honest pitch. A homeowner in the 650 band may see a payment slightly above their current bill in year one but below it after rate increases. Presenting the numbers accurately by tier prevents the cancellation and complaint cycle that destroys installer reputations.
One caution: credit tier data is a snapshot, not a guarantee. Scores change, and lenders apply their own underwriting. Treat the tier as a planning input that shapes your presentation, never as a promise of approval. If a homeowner insists their score has improved, run a soft pull with a lending partner before committing to a financing-based proposal.
When To Disqualify A Solar Lead Early
Disqualification is a revenue strategy, not a rejection strategy. Every hour spent on a lead that cannot close is an hour stolen from a lead that can. The bill and credit fields give you enough information to make that call within the first two minutes of review, and doing so keeps your cost per acquisition under control.
Consider early disqualification or long-term nurture in these situations. A bill under $80 per month with no EV, pool, or planned electrification usually produces a system too small to support a full sales cycle, though it may qualify for a referral or a small partial-offset project. A credit tier below 600 with no co-borrower and no cash interest rarely converts. A renter who does not control the roof is not a solar buyer regardless of bill size. An address with a roof age over 20 years, if disclosed, usually needs replacement first, which changes the project scope entirely.
The flip side matters just as much. Do not disqualify a lead because the bill range seems modest if the homeowner mentions a planned EV purchase, a new heat pump, or a home addition. Those disclosures change the load profile and often justify a larger system. Similarly, a low credit tier with a stated co-signer is worth a call. The data filters the obvious mismatches; the phone call resolves the ambiguous ones.
Document every disqualification with a reason code in your CRM. Over time, those codes reveal which lead sources deliver the best bill and credit profiles for your market, which is exactly the data you need when negotiating lead purchases or adjusting your filters. Contractors who track disqualification reasons consistently reduce their effective cost per installed system by double digits.
Balancing Qualification Depth Against Response Speed
Solar leads decay faster than almost any other home improvement lead category. A homeowner researching solar on Monday may sign with a competitor by Thursday. Every minute between lead delivery and first contact reduces the odds of a conversation, and every additional qualification question during that first contact reduces the odds of booking a survey. The bill and credit data exist precisely so you can skip questions and move fast.
The practical workflow looks like this. When a lead arrives, check the bill range and credit tier first. If both clear your minimum thresholds, call within five minutes. Open with a statement that demonstrates you already know their situation: mention their approximate electric bill and ask whether they have considered how much of it solar could offset. That single sentence signals competence and skips two screening questions. If the lead falls below threshold, either place it in a nurture sequence or mark it disqualified and move on. Either way, you have spent seconds, not hours.
Speed also interacts with financing. Homeowners in higher credit tiers often have multiple solar quotes in progress. The installer who calls first, presents accurate numbers, and offers a clear next step usually wins, even against a lower-priced competitor. Bill and credit data let you be that first caller with a relevant pitch instead of a generic script. For contractors who want to understand how performance-based call acquisition fits alongside purchased leads, platforms like PayPerCallMarketing specialize in connecting advertisers with publishers to generate qualified phone calls, which can complement a lead-buying strategy when phone volume matters as much as form fills.
Set internal service level agreements around the data. A reasonable standard is first contact within five minutes for high-bill, high-credit leads, within 30 minutes for mid-tier leads, and same-day nurture enrollment for below-threshold leads. Review those SLAs weekly against close rates. If high-tier leads are closing at 30 percent and mid-tier at 12 percent, your qualification thresholds and your outreach speed are working together as intended.
Finally, remember that bill and credit data are tools for prioritization, not substitutes for human judgment. A homeowner with a modest bill and excellent credit may be planning a major renovation that doubles their consumption. A homeowner with a large bill and challenged credit may have a spouse with a stronger profile. The data tells you where to look first; the conversation tells you what is actually true. Installers who combine disciplined data filtering with fast, human follow-up consistently outperform those who rely on either alone.
Solar lead data is only as valuable as the process built around it. Use the electricity bill range to size the opportunity, use the credit tier to choose the financing path, disqualify early when the numbers do not work, and protect response speed above all else. Contractors who treat these fields as the foundation of their qualification workflow spend less per installation and close more of the leads they already pay for.